The guideHaven't started2 min read
Are you ready for this journey?
A worksheet for the why, the when, and the why-not. The emotional part is the expensive part.
By Paddy Carroll · Founder, HomePlanner
The hunt for a home is emotional, and emotion is what makes people pay too much for the wrong property. The defence is deciding what you want while nothing is at stake, writing it down, and reading it back when you're standing in a place you have fallen for.
Clarify your why
- 1What is this purchase for? Somewhere to live, an investment, or somewhere to live in now and rent out later. Pick one.
- 2If it's somewhere to live: what does it have to do for you? Location, space, the commute, the schools. What would you give up to stay in budget, and what would you never give up?
- 3If it's an investment: are you willing to buy in an area that stacks up on the numbers but that you wouldn't choose for yourself? Can you handle a tenant, or will you pay someone to?
- 4What's the financial goal? Lowest possible repayment, best rental yield, best growth prospects, or simply getting in as soon as you can. These pull in different directions.
- 5Why now? Write the honest answer. "Everyone keeps asking" is a reason, but it isn't a good one.
Stress-test it before the market does
Five questions worth answering honestly while nothing is at stake. Decide your answer before you open each one.
What happens if rates rise two percentage points?
Work out the actual repayment, not the feeling. Lenders already assess you at roughly three points above the offered rate, so if that number frightens you, you are looking above your real budget rather than at a rate risk. This is the single most useful sum in the whole guide, and the borrowing power calculator does it with your figures.
What if one income stops for six months?
Illness, redundancy, a baby. This is what the emergency fund is for, and it is why it sits outside the deposit rather than being swept into it at the last minute. Three to six months of living costs, kept separate and untouched.
What if you have to sell in three years?
Selling costs money — agent's commission, marketing, legal, and stamp duty already paid and unrecoverable. Over a short horizon those can easily exceed any growth. If there is a real chance you move within a few years, that is an argument for renting longer, not for buying smaller.
Could you still live your life at this repayment?
A lender's maximum is what they will risk, not what you should borrow. Take the repayment off your income and look at what is left against what you actually spend. A house you cannot afford to leave is not a good outcome.
Are you buying because you want to, or because you are being asked about it?
Both are common and only one survives a bad year. There is no wrong answer here, but there is a dishonest one, and the cost of the dishonest one is the largest purchase of your life.
And your why not
This is a large financial and emotional commitment, and being clear-eyed about the risks is how you plan around them rather than being surprised by them.
- It ties up cash you may want for something else. Keep an emergency fund outside the deposit; three to six months of living costs is the usual advice.
- It makes you less mobile. Selling costs money and takes time, so a job in another city gets harder.
- Repayments are not fixed forever. A variable rate can move, and a fixed rate ends.
- Maintenance is now yours. Budget for the hot water system nobody thinks about until it goes.
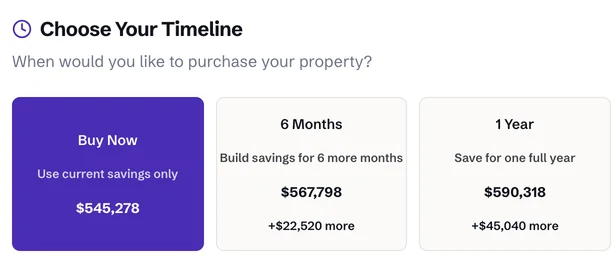
- Today's budget: what a lender would lend, plus your cash
- What each extra six months of saving adds
Before you move on
- You've written down your main purpose for buying
- You know what you'd compromise on and what you wouldn't
- You've named the risks and how you'd handle each one
- You have a target date, even if it's years out